Published September 29, 2026
Can I Actually Afford to Buy My First Home?
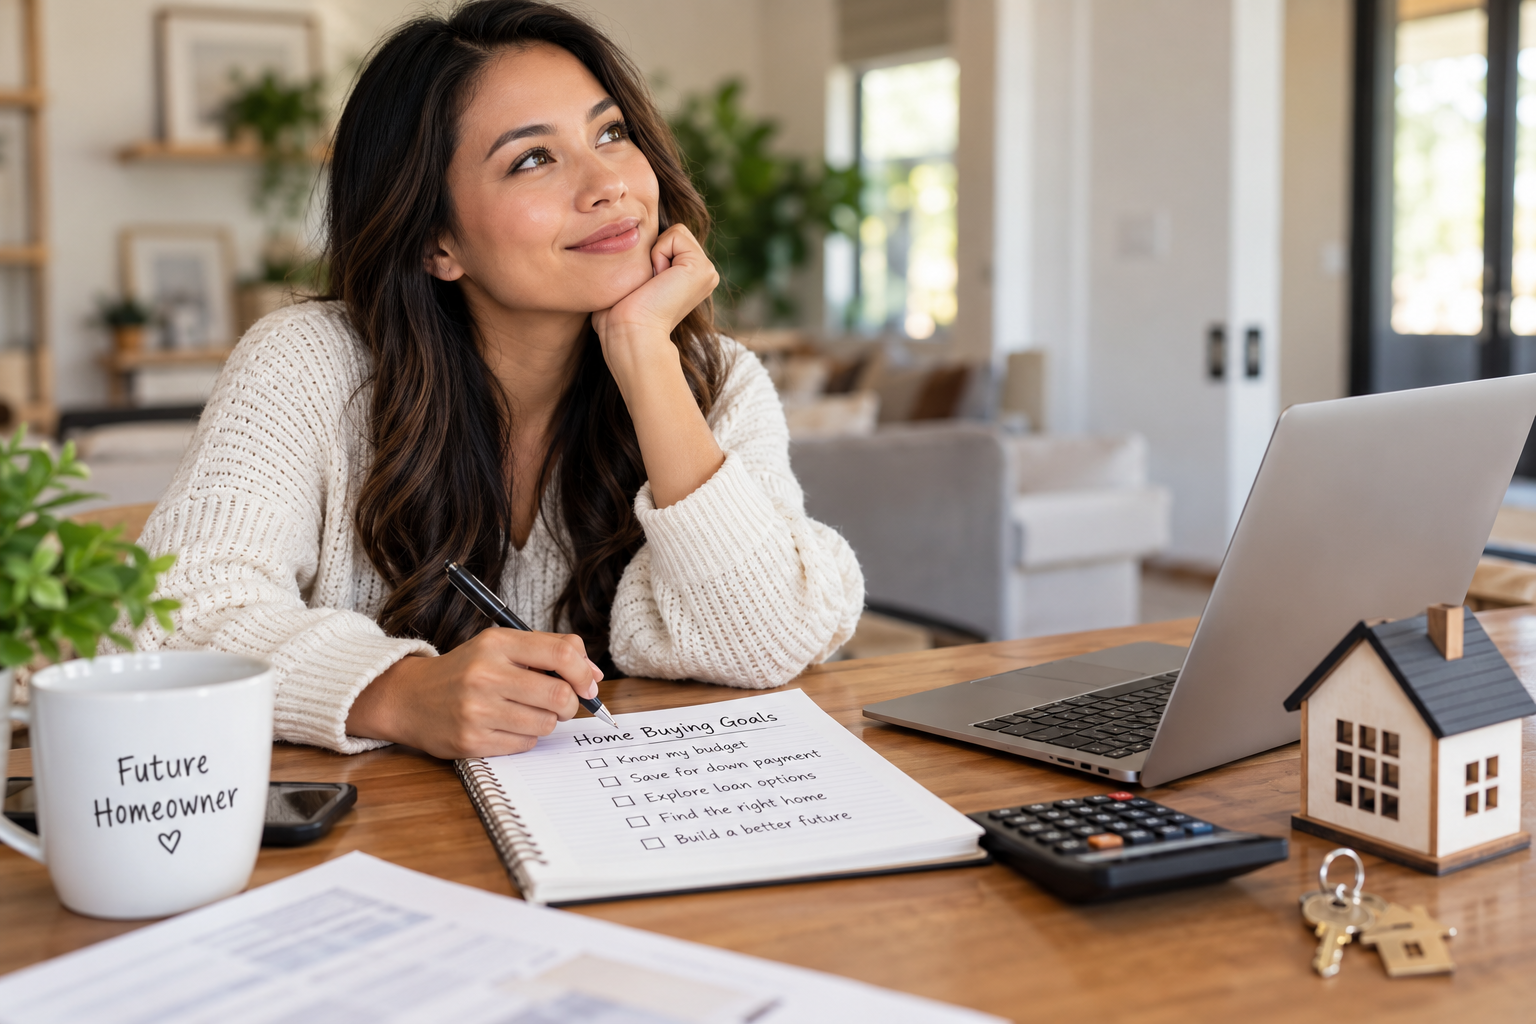
One of the biggest questions first-time home buyers are asking right now is:
“Can I actually afford to buy my first home?”
With home prices, mortgage rates, and everyday expenses getting so much attention, it’s understandable why many renters assume buying a home simply isn’t possible for them right now.
But there’s an important difference between knowing you can’t afford to buy a home and assuming you can’t afford one.
Before you count yourself out, I believe it’s worth finding out what the numbers actually look like for you.
You may be closer than you think.
If you prefer to watch a video click here: Can I Actually Afford to Buy My First Home?
A First-Time Buyer Who Thought Homeownership Was Out of Reach
A few years ago, a friend referred me to a wonderful lady named Progress who wanted to buy her first home.
Progress worked—and still works—for the State of Texas. Like many first-time buyers, she wasn’t making a huge income,
and she wasn’t sure whether buying a home was even possible for her.
So we sat down.
We looked at her numbers. We talked about what she could comfortably afford. We explored the options available to her.
And a few months later, Progress bought her very first home.
I still love her story because she could have easily decided that homeownership wasn’t possible before ever investigating her options.
Instead, she took the time to find out.
And she discovered she was closer than she thought.
First-Time Home Buyers Are Facing a Different Market
According to the National Association of REALTORS® 2025 Profile of Home Buyers and Sellers, first-time buyers represented only 21% of home buyers, the lowest share since NAR began collecting this data in 1981. Historically, before 2008, first-time buyers represented about 40% of the market.
That tells us something important.
Today's first-time buyers are navigating a very different environment than many previous generations of buyers.
Mortgage rates, home prices, available inventory, and affordability have all affected the home-buying experience.
The NAR report specifically identified limited inventory and affordability challenges during the period studied.
So comparing what you can afford today with what someone bought five or ten years ago may not be particularly helpful.
Your decision needs to be based on today's numbers and your situation.
Don't Look at the Interest Rate Alone
I often hear:
“Interest rates are too high. I'm going to wait.”
The interest rate absolutely matters because it affects your monthly mortgage payment and purchasing power.
But it isn't the only number that matters.
Your income, existing debt, available savings, credit profile, property taxes, insurance, financing structure, potential seller or builder incentives, and the price of the home can all affect what buying looks like for you.
That's why I encourage potential first-time buyers to ask themselves a different question:
If the interest rate weren't the issue, could I see myself owning a home within the next 8–12 months?
If your answer is yes, you don't necessarily need to go buy a house tomorrow.
But you may want to start exploring your options today.
Start With What You Can Comfortably Afford
One of the biggest mistakes I see buyers make is starting with:
“What's the maximum amount I can qualify for?”
I'd rather start with:
“What monthly housing payment would allow me to own a home and still comfortably live my life?”
Those aren't necessarily the same number.
Homeownership shouldn't mean spending every dollar you have on the house.
You still have groceries, transportation, travel, savings, emergencies, family expenses—and hopefully a life outside of your mortgage payment.
Understanding your comfortable monthly payment gives you a much better starting point for exploring a realistic home price range.
What Is Actually Stopping You?
If you're thinking about buying your first home, ask yourself what is really holding you back.
Is it the monthly payment? The down payment? Your credit? Existing debt? The interest rate? Or do you simply not know where to begin?
Sometimes the obstacle is real and requires time and planning.
But sometimes the obstacle is based on an assumption.
For example, many potential buyers believe they need 20% down before they can even consider purchasing a home.
That's exactly what we'll explore next in my First-Time Home Buyer Series.
You Don't Have to Be Ready to Buy
Finding out you're not financially ready today isn't a failure.
It gives you something extremely valuable: a plan.
Maybe you're ready now.
Maybe you're six months away.
Maybe you need another year to save, reduce debt, improve your credit profile, or prepare for the monthly payment you want.
I'd rather have you know what needs to happen than spend another year assuming homeownership isn't possible.
My goal isn't to convince you to buy a house.
My goal is to help you understand your numbers and your options so you can decide for yourself.
If you have questions about buying your first home, visit Jan Lee Homes or learn more about me at Meet Jan Lee.
Even if you're outside Texas, I'm happy to help answer general questions and point you in the right direction.
You don't have to be ready to buy. You just need to be ready to find out.
You may be closer than you think.
Next in the First-Time Home Buyer Series
Do I Really Need 20% Down to Buy My First Home?
We'll look at where the 20% assumption comes from, what recent first-time buyers actually put down, and why your down-payment strategy should be based on your finances—not a number you've heard repeated online.
Jan Lee
| Jan Lee Homes
or another way